Foreigners, including US citizens, can buy a house in Japan with the same legal rights as Japanese citizens, and need no visa, residency or citizenship. A typical purchase takes 60 to 90 days, and fees and taxes add about 4 to 6% to the price. Since 1 April 2026, non-residents must file a FEFTA report within 20 days of buying.
Key Facts for 2026
- There are no nationality restrictions on buying property in Japan; US, UK, Australian and other buyers have the same rights as Japanese citizens.
- Fees and taxes typically add 4 to 6% to the purchase price, plus 1 to 2% in bank fees if you use a mortgage.
- The brokerage fee for buying is capped at 3% + ¥60,000 + 10% consumption tax.
- Non-residents must file FEFTA Form 22 via the Bank of Japan within 20 days of acquisition. From 1 April 2026 this also applies to homes bought for the buyer’s own use, which were previously exempt. This does not effect ownership rights.
- From 5 October 2026, every individual buyer must state their nationality when registering ownership. The rule records nationality and does not limit who can buy.
- A typical purchase, from offer to keys, takes 60 to 90 days.
Can a Foreigner Buy a House in Japan?
Foreigners buy houses in Japan with the same legal rights as Japanese citizens, and do not need to be resident, hold a visa or have lived in Japan before. Property registration follows the same rules for every buyer regardless of nationality, and there is no quota on how many units in a building foreigners can own.
The right to buy is separate from the right to live in Japan, so many international buyers complete their purchase during a visa-free visit. Nationals of 74 countries and regions can enter without a visa for short stays, including the United States, the United Kingdom and Australia (Ministry of Foreign Affairs list, 1 September 2025). Owning a home does not grant residency, so living in it long term still requires a separate work, spouse or business visa.

Can an American Buy a House in Japan?
US citizens buy property in Japan on the same terms as Japanese citizens and every other nationality, with no extra approval, quota or minimum purchase price. The United States is on Japan’s visa exemption list with a 90-day stay, so an American buyer can fly in, view homes and sign a contract on one trip.
Under Japan’s Foreign Exchange and Foreign Trade Act, a foreign national counts as a resident once they work at an office in Japan or six months after arriving, according to Ministry of Finance guidance. An American living in the US is a non-resident. Non-residents file FEFTA Form 22 after the purchase, appoint a tax representative to receive the annual property tax bill, and usually buy in cash or through the specialist lenders in the non-resident column of the financing table below. Americans already working in Japan follow the resident rules.
US citizens are taxed on worldwide income wherever they live. Rent from a Tokyo apartment is taxed first in Japan, where the property sits, and must also go on your US return, where a foreign tax credit can offset the Japanese tax. A home held in your own name is not reported on IRS Form 8938, but a Japanese bank account used for rent or bills must go on an FBAR if your foreign accounts total more than $10,000 at any point in the year. A US tax adviser who handles overseas property can confirm your position.
How Do You Buy a House in Japan? Step-by-Step Process
Buying a house in Japan as a foreigner takes about 60 to 90 days from first offer to keys, and the eight steps below are the same for every nationality. Where you live changes only the financing options in step 3 and the FEFTA report after step 8.
1. Choose an Experienced Bilingual Agent
In Japan, your real estate agent does work that in many other countries belongs to a lawyer: market research, viewings, price negotiation, contract drafting, translating and explaining Japanese documents, and coordinating the title transfer. A standard residential purchase involves no buyer-side lawyer or notary, so your agent and the judicial scrivener (司法書士, shihō shoshi) share the legal work.
Tell your agent your target area, property type, budget and timeline at the first meeting, and ask whether they can show off-market homes as well as advertised listings.
Under the Real Estate Brokerage Act (宅地建物取引業法, takken gyōhō), only brokers licensed by a prefectural governor or MLIT can handle property transactions in Japan. Every office must employ a Real Estate Transaction Specialist (宅建士, takken-shi) to deliver the Explanation of Important Matters before you sign. A licensed agent can also search REINS, the national listings database open to licensed brokers. Ask any agency for its licence number and check that the takken-shi handling your file works for that agency, because the Act prohibits licence-lending. Housing Japan is licensed by the Tokyo Metropolitan Government under Tokyo Governor Licence (3) No. 98912.
2. View Properties On-site

3. Talk to a Bank About Financing
Cash buyers can skip this step. Anyone who needs a mortgage should speak to a bank before making an offer, since an informal pre-approval strengthens the offer.
Mainstream Japanese lenders look at residency status and taxed income earned in Japan rather than nationality, so a Japanese citizen earning entirely overseas faces the same obstacle as a foreign national. Buyers without Japanese income are limited to the specialist and overseas lenders in the right-hand column.
| Permanent / Special Permanent Resident | Long-term visa, non-PR | Non-resident overseas | |
|---|---|---|---|
| Access | Full mainstream market | Restricted, specialist products | Very limited |
| Typical requirement | Same as a Japanese citizen | Usually 2 to 3 years’ employment in Japan, stable income | Japan income normally absent, so most buy cash |
| Flat 35 | Available | Not available – JHF requires PR or Special PR | Not available |
| Lenders | Mizuho, MUFG, SMBC, Resona, Flat 35 (JHF) | SMBC Trust Prestia, Tokyo Star, Suruga, SBI Shinsei, AEON Bank | Yen Loans, ORIX Asia, UOB Singapore, CTBC, Sumitomo Mitsui Trust |
| Typical LTV | 100 to 110% | 80% | 50 to 70% |
| Rate, Oct 2026 | 1.2% to 1.5% variable; Flat 35 3.83% fixed | 1.2% to 3.9% variable (Aug 2026) | 3.1% to 4.7% variable (Aug 2026) |
Permanent resident rates are the lowest variable rates for new loans at MUFG, Resona, Mizuho and SMBC in October 2026, and the October 2026 Flat 35 rate for a 21–35 year loan of up to 90% of the price. MUFG will revise its variable base rate from 1 December 2026, following the Bank of Japan’s rise to 1.25% on 18 September. Other columns show August 2026 figures, as specialist and overseas lenders set rates for each applicant. Confirm current terms with each lender.
4. Submit a Letter of Intent
Once you choose a property, your agent sends the seller a Letter of Intent (買付証明書, kaitsuke shōmeisho) setting out your offer price and conditions. Sellers usually consider letters in the order they arrive, so having financing lined up gives you an advantage.
5. Negotiate Terms and Sign the Purchase Contract
Your agent negotiates the price, payment timing, fixtures and handover conditions with the seller’s side, which usually takes one to two weeks.

6. Review the Explanation of Important Matters
Before you sign, a takken-shi reads you the Explanation of Important Matters (重要事項説明書, jūyō jikō setsumeisho), which covers the ownership type, building condition, management association rules, zoning and cancellation terms. Reputable agencies provide an English translation, but only the Japanese contract and disclosure have legal effect, so you need a bilingual agent who can explain the originals.
Both parties then sign the purchase contract, and the buyer pays a deposit (手付金, tetsukekin) of typically 5 to 10% of the price directly to the seller. Buyers used to escrow are often surprised by this. The deposit also sets the exit terms: under Article 557 of the Civil Code, until the other side starts performing the contract, the buyer can cancel by forfeiting the deposit and the seller by repaying double. Mortgage buyers pay this deposit in cash too.
7. Final Loan Approval (Mortgage Buyers Only)
Final loan approval comes after the contract is signed. You then sign the loan agreement at the bank, usually on a weekday in a session lasting several hours. Cash buyers move straight to settlement.
8. Final Settlement and Title Transfer
Settlement usually takes place at the buyer’s bank with a judicial scrivener present. The buyer transfers the balance to the seller, the seller hands over the keys, and the scrivener files the ownership transfer at the Legal Affairs Bureau. You become the legal owner when your name enters the property register, usually within a few business days, and not when you sign the contract.
After settlement, non-residents have 20 days to file FEFTA Form 22 (see below), and whoever is on the register on 1 January receives that year’s fixed asset tax bill.
Housing Japan’s current Tokyo listings cover homes and apartments for sale across central Tokyo, and our agents can also show off-market properties on request. Use the button below to talk through your budget and timeline before you start viewing.
How Much Does it Cost to Buy a House in Japan?
Fees and taxes on a home purchase in Japan typically add about 4 to 6% to the price for a cash buyer. The biggest variable is whether the property qualifies for reduced tax rates. Mortgage buyers add 1 to 2% in bank fees. The table uses 2026 rates from the National Tax Agency, MLIT and the Tokyo Metropolitan Government.
| Cost | What it is | Typical rate (2026) |
| Brokerage fee | Paid to your real estate agent on a successful purchase. Capped by MLIT. | 3% of price + ¥60,000 + 10% consumption tax (≈3.3%). Properties at or below ¥8m: up to ¥330,000 including tax, by prior agreement |
| Registration & licence tax (land) | Paid to register the land transfer at the Legal Affairs Bureau. | 1.5% of assessed value (reduced rate extended to 31 March 2029); standard rate 2.0% |
| Registration & licence tax (building) | Paid when ownership of the building is transferred or first registered. | 2.0% standard; 0.1% to 0.3% reduced for qualifying homes (until 31 March 2027) |
| Real estate acquisition tax | One-off prefectural tax billed 3 to 6 months after registration. | 3% on residential land and homes; 4% on non-residential buildings (3% rate runs until 31 March 2027) |
| Stamp duty | Revenue stamp affixed to the purchase contract. | ¥30,000 for contracts of ¥50m to ¥100m; ¥60,000 for ¥100m to ¥500m. Reduced rates apply to contracts executed to 31 March 2027 |
| Judicial scrivener fee | Pays the legal professional who handles the title transfer. | ¥80,000 to ¥200,000 (more for mortgages) |
| Annual fixed asset tax | Paid every year by the registered owner as of 1 January. | 1.4% of assessed value |
| Annual city planning tax | Applies to property within designated urban planning zones. | Up to 0.3% of assessed value |
Most of these taxes are calculated on the property’s assessed value (固定資産評価額, kotei shisan hyōkagaku), not the purchase price. Assessed values sit well below market prices, so the real tax bill is lower than the headline rates suggest. The acquisition tax bill arrives 3 to 6 months after registration, so set funds aside for it.
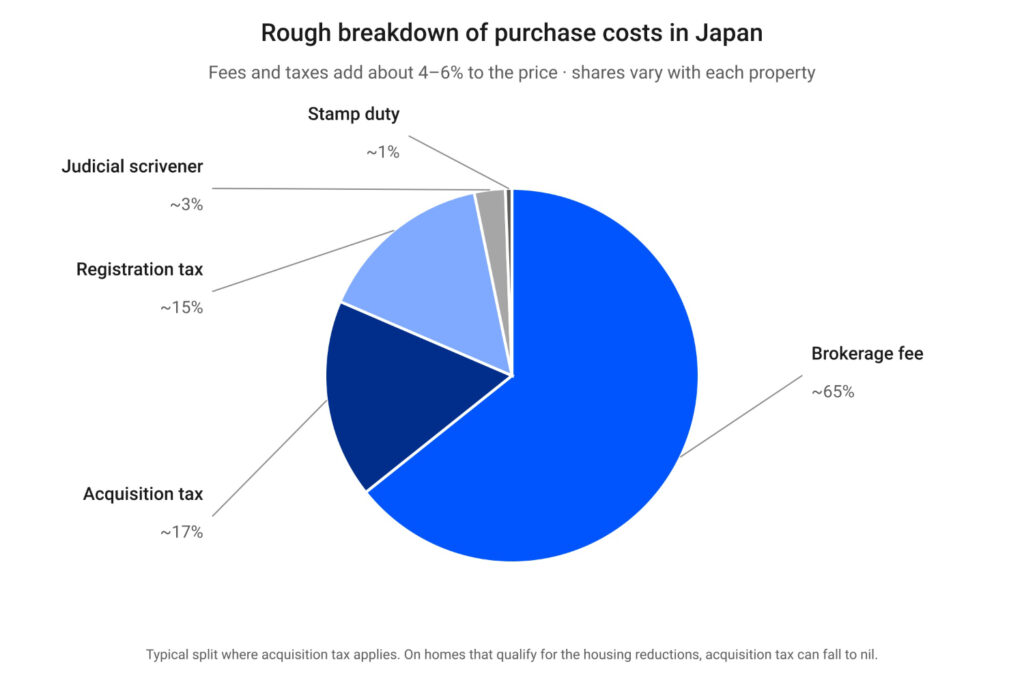
| Cost | Rough share of total purchase costs |
|---|---|
| Brokerage fee | ~65 to ~80% |
| Acquisition tax | 0 to ~20% |
| Registration tax | ~10 to ~15% |
| Judicial scrivener | ~2 to ~5% |
| Stamp duty | ~1% |
Rough guide only. Shares vary with each property’s assessed value, size and whether reduced tax rates apply. The example below shows one property in exact figures.
The brokerage fee is usually the largest single cost, at roughly two-thirds to four-fifths of the total. In Japan the broker also drafts the contract, prepares the legal disclosures and coordinates the title transfer, work that a lawyer would do in many other countries.
What does this look like on a real purchase?
Illustrative only: a ¥100,000,000 resale condominium in central Tokyo built after 1981, bought in cash, with assessed values (固定資産評価額) assumed at ¥40m for the land share and ¥10m for the building and a scrivener fee of ¥140,000. The first column is a home that qualifies for the housing tax reductions, assuming the deductions cover the acquisition tax in full. The second is a home that does not, for example because its floor area is under 50 sqm.
| Item | Basis | Qualifying home | Non-qualifying home |
|---|---|---|---|
| Brokerage fee | ¥100m × 3% + ¥60,000, plus 10% tax | ¥3,366,000 | ¥3,366,000 |
| Registration tax, land | ¥40m × 1.5% | ¥600,000 | ¥600,000 |
| Registration tax, building | ¥10m × 0.3% (qualifying) or 2.0% | ¥30,000 | ¥200,000 |
| Acquisition tax, land | ¥40m × ½ × 3%, less housing deduction | ¥0 | ¥600,000 |
| Acquisition tax, building | ¥10m × 3%, less housing deduction | ¥0 | ¥300,000 |
| Stamp duty | Reduced rate, ¥50m to ¥100m band | ¥30,000 | ¥30,000 |
| Judicial scrivener | Typical range ¥80,000 to ¥200,000 | ¥140,000 | ¥140,000 |
| Total | ¥4,166,000 (4.2% of price) | ¥5,236,000 (5.2% of price) |
Mortgage buyers add 1% to 2% in bank fees to either total. A different price, building age, floor area or assessed value changes every line, so ask your agent for an estimate on the specific property.
Our guide to buying taxes and fees explains each tax line in more detail, including the conditions for the reduced rates.
After you buy, you pay fixed asset tax and city planning tax each year, monthly management and repair reserve fees for a condominium, and loan repayments if you borrowed. Our Yen Loan Calculator estimates monthly payments.
What Documents Do You Need to Buy a House in Japan?
The documents you need depend on whether you live in Japan or abroad. Your agent and judicial scrivener will confirm the exact list for your purchase.
If You Live in Japan
- Residence card and passport
- Inkan (registered personal seal) and seal certificate (印鑑登録証明書)
- Proof of income, three years of records if applying for a mortgage
If You Live Outside Japan
- Passport
- Notarised affidavit in place of the inkan and seal certificate
- Proof of address, often a utility bill or bank statement
- From April 2026: the information needed for the FEFTA Form 22 filing (see below)

What Changed for Foreign Buyers in 2026?
Japan added two reporting steps for property buyers in 2026: wider FEFTA reporting for non-residents from 1 April, and nationality disclosure at registration from 5 October. Neither restricts your right to buy.
1. FEFTA Form 22 Reporting for Non-Residents
Under Japan’s Foreign Exchange and Foreign Trade Act, a non-resident who acquires real estate in Japan must submit Form 22 to the Minister of Finance through the Bank of Japan within 20 days. The report itself is long-standing. On 1 April 2026 the exemption for a home bought as the buyer’s own residence was removed, so every acquisition is now reportable regardless of purpose, price or size. The 20 days usually run from the contract date or the ownership transfer date, and a deadline that falls on a non-business day moves to the next business day. The form is in Japanese only, so a resident agent such as your licensed broker normally files it, on paper or online. Not filing can bring a fine of up to ¥500,000, but the report is not an approval and does not hold up the purchase.
2. Nationality Disclosure at Registration
The Ministry of Justice amended the Real Property Registration Rules (不動産登記規則) by an ordinance promulgated on 31 March 2026 (MOJ Ordinance No. 23). From 5 October 2026, any individual who becomes a registered owner through a preservation, transfer or correction of ownership registration must state their nationality. The rule applies equally to Japanese and foreign buyers. The Ministry keeps nationality in an internal search file, and it does not appear on the public property register (登記簿).
What did NOT change: foreign nationals still have the same ownership rights as Japanese citizens. There is no foreign ownership cap and no minimum investment, and buying a house does not give you a visa or residency.
For a short summary of the ownership rules with the Ministry of Finance source, see our resource guide Can Foreigners Buy Property in Japan?
What Should Foreigners Know Before Buying a House in Japan?
Non-Resident Owners Need a Tax Representative
If you live outside Japan, you must appoint a tax representative (納税管理人, nōzei kanrinin) with a Japanese address to receive your fixed asset tax bill each year. Foreign owners often use their judicial scrivener, their agent or a mail-handling service. If you plan to let the home, Housing Japan’s property management service can handle tenants and rent collection.
Should You Buy in Japan for Short-Term Rental Income?
Japan’s Private Lodging Business Act (住宅宿泊事業法), in force since June 2018, caps short-term rentals at 180 days a year. Many condominium management associations ban short-term rentals in their bylaws, and Tokyo wards including Shinjuku, Shibuya and Minato limit the days minpaku can operate in residential zones. Investors who want short-stay income typically take one of three routes: buying a whole apartment building, developing in a National Strategic Special Zone (特区民泊) that allows year-round operation, or running under a hotel or ryokan licence (旅館業法) instead of minpaku.
Housing Japan’s sister company, Ken’s Place, specialises in this work across central Tokyo, including Minami-Azabu, Roppongi, Azabu-Juban, Omotesando and Akasaka. It helps investors with business planning, design, licence applications and day-to-day operation. If short-term rental income is part of your plan, bring both teams in early so the purchase fits the operating model.

How Does the Process Differ for Residents and Non-Residents?
Residents and non-residents have identical ownership rights. They differ in the ID they use, which banks will lend to them and which reports they file.
| Item | Resident in Japan | Non-resident overseas buyer |
|---|---|---|
| Right to buy | Same as Japanese citizens | Same as Japanese citizens |
| ID required | Residence card, passport, inkan | Passport plus a notarised affidavit in place of an inkan |
| Mortgage access | Mainstream banks for permanent residents; specialist lenders for other visa holders | Generally cash-only; a small number of lenders work with non-residents |
| FEFTA reporting | Not required | Form 22 to the Bank of Japan within 20 days of acquisition (from April 2026) |
| Tax representative | Not required | Required to receive property tax bills in Japan |
Do Properties in Japan Lose Value? Not in Central Tokyo
Standard advice holds that a Japanese building loses almost all its value within 20 to 30 years, and that is true of wood-frame housing in much of the country. It has not described central Tokyo for some years.
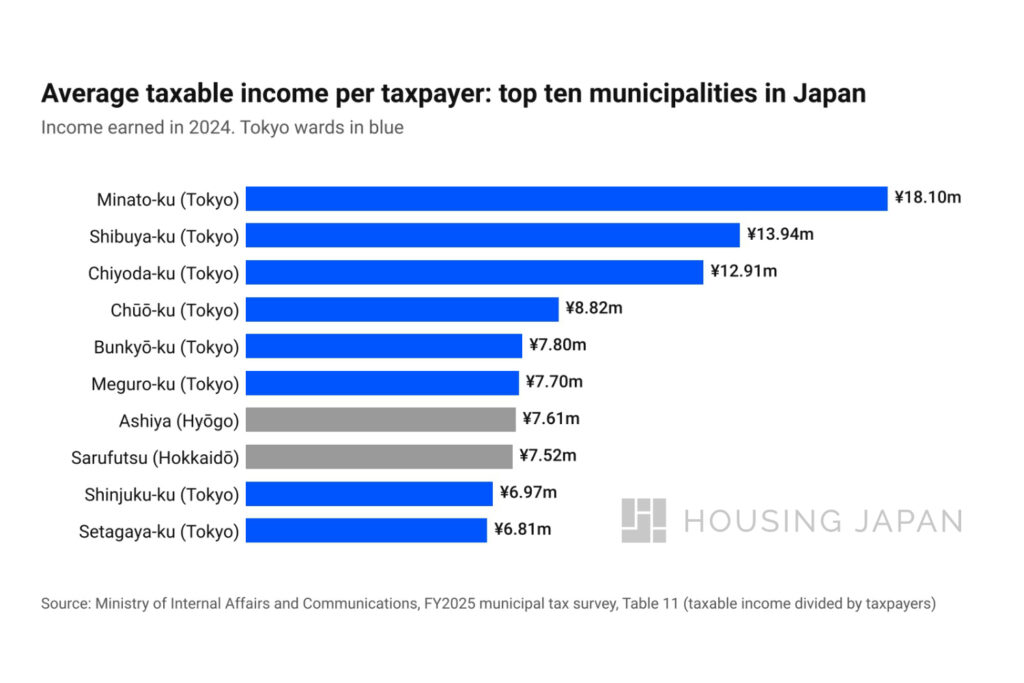
In the 2026 official land price survey (公示地価, valued at 1 January 2026 and published 17 March 2026), Tokyo’s all-use average rose 8.4%, up from 7.3% the previous year. Residential land rose 6.5% and commercial land 12.2%, the fifth consecutive annual increase. Of 2,503 comparable survey points across Tokyo, 2,445 rose and 14 fell, and within the 23 wards all 1,530 continuing points rose. Tokyo residential land averaged ¥565,100 per sqm, the highest of Japan’s 47 prefectures. Akasaka 1-14-11 in Minato-ku was the most expensive residential point in the country for the ninth consecutive year, at ¥7.11m per sqm, up 20.5%.
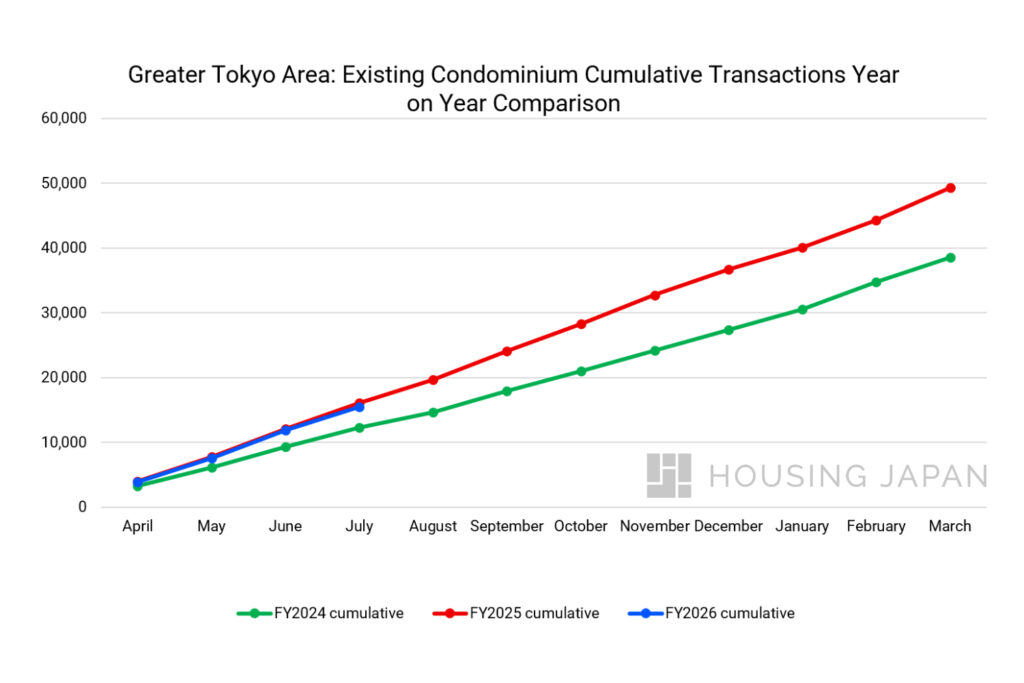
The prefectural land price survey (基準地価, valued at 1 July 2026 and published 16 September 2026) showed the same pattern six months later. All 726 comparable survey points in the 23 wards rose and none fell, residential land in the 23 wards rose 8.7%, and Minato-ku recorded the highest residential rise at 16.3%, according to the Tokyo Metropolitan Government. Resale condominium contracts in Tokyo reached 25,601 in the year to June 2026, up 11.6% on the previous year (REINS data compiled by the Tokyo Metropolitan Government).
You can check the official price for any specific site on MLIT’s Real Estate Information Library.
Depreciation remains the norm for wood-frame housing outside Japan’s major urban land markets, and these survey results cover one market over one period, not a forecast. Resale condominium prices per sqm across Greater Tokyo were 1.5% lower in July 2026 than a year earlier, according to REINS. Borrowing costs are also rising: the Bank of Japan lifted its policy rate to 1.25% on 18 September 2026, a 31-year high.
For owner-occupiers, the draw is daily life in the city, whether on a quiet residential street in Hiroo or Azabu or in an apartment tower in Minato or Shibuya. Our Tokyo area guides compare neighbourhoods for international buyers.

Ready to Buy a House in Tokyo?
Housing Japan has helped international buyers purchase homes in Tokyo since 2000, under Tokyo Governor Licence (3) No. 98912. Our bilingual team, including in-house takken-shi, handles negotiation, the Explanation of Important Matters, FEFTA filing and tax representative arrangements. Use the contact form below to start a confidential conversation about your purchase.
Including off-market properties available on request.
Speak to a licensed, bilingual Tokyo agent:
Q&A: Buying a House in Japan as an Expat
Can a foreigner buy a house in Japan in 2026?
Foreign nationals can buy land, houses and apartments in Japan with the same legal rights as Japanese citizens, without a visa or residency. Since 1 April 2026, non-residents must file FEFTA Form 22 within 20 days of buying, and since 5 October 2026 every individual buyer states their nationality at registration. Neither rule restricts foreign purchases.
Can a US citizen buy a house in Japan?
US citizens can buy a house in Japan with the same rights as Japanese citizens, and can enter visa-free for up to 90 days to view homes and sign. An American living in the US counts as a non-resident, so files FEFTA Form 22 after buying. Rent from the property is taxed in Japan and must also be reported to the IRS. Property held in your own name is not reported on IRS Form 8938, but a Japanese bank account can trigger an FBAR filing if your foreign accounts exceed $10,000 at any point in the year.
Do I need a visa or residency to buy a house in Japan?
You do not need a Japanese visa or residence permit to buy property in Japan. Nationals of 74 countries and regions, including the United States, Australia and most of the EU, can enter visa-free for up to 90 days, long enough to view homes and sign a contract. Some countries can extenf this 90 days by another 90 days, read this guide on Extending your Visa Free Tourist Entry Permit in Japan. Buying a house does not grant a visa or the right to live in Japan long term.
How much does it cost to buy a house in Japan?
Fees and taxes on a home purchase in Japan typically add 4 to 6% to the price, plus 1 to 2% in bank fees if you take a mortgage. The largest single cost is the brokerage fee, capped at 3% of the price plus ¥60,000 plus 10% consumption tax. You also pay registration tax (1.5% on land at the reduced rate, extended to 31 March 2029), real estate acquisition tax (3% on residential land and homes), stamp duty and the judicial scrivener’s fee.
Can foreigners get a mortgage in Japan?
Permanent residents of Japan can borrow from mainstream banks, including Flat 35, on the same terms as Japanese citizens. Other foreign residents usually need two to three years of employment in Japan and borrow from specialist lenders at higher rates. Non-residents living overseas have few options, typically at loan-to-value ratios of 50 to 70%, so most buy in cash.
How long does it take to buy a house in Japan?
A standard purchase in Japan takes 60 to 90 days from the Letter of Intent to settlement and key handover, and cash buyers can sometimes close in 30 to 45 days. Title registration at the Legal Affairs Bureau usually completes within a few business days of settlement.
What is FEFTA Form 22 and do I need to file it?
FEFTA Form 22 is the report a non-resident files with the Minister of Finance, through the Bank of Japan, within 20 days of acquiring real estate in Japan. Since 1 April 2026 it applies to every purchase, including a home for your own use. Your licensed agent normally files it for you. Residents of Japan do not file it. The report is not an approval and does not delay completion.
Are there areas in Japan where foreigners cannot buy property?
No area bars foreign buyers specifically. The Important Land Survey Act covers land near defence facilities and remote border islands for all buyers, Japanese or foreign. In its Special Monitoring Zones, both parties must notify the Cabinet Office before signing a contract for land or buildings of 200 sqm or more.
Do I have to pay tax in Japan if I rent out my property?
Rental income from Japanese real estate is taxed in Japan wherever the owner lives. Tenants paying rent to a non-resident owner withhold 20.42% and pay it to the tax office, unless the tenant is an individual renting the home to live in. Owners then file an annual Japanese tax return.Tax treaties, including the US-Japan and UK-Japan treaties, usually prevent double taxation. A licensed Japanese tax accountant should handle the filings.
Can I do Airbnb with a property I buy in Japan?
Japan’s Private Lodging Business Act caps minpaku short-term rentals at 180 days a year. Many condominium management associations ban short-term rentals in their bylaws, and Tokyo wards including Shinjuku, Shibuya and Minato limit the days minpaku can operate in residential zones. Confirm the building bylaws and ward rules in writing before buying for short-term rental income.
Do properties in Japan lose value?
Whether a Japanese property loses value depends on where it is. Wood-frame houses across much of Japan still lose most of their building value within 20 to 30 years, but central Tokyo land has risen steadily. All 1,530 continuing survey points in the 23 wards rose in the January 2026 official land price survey, and all 726 rose again in the July 2026 prefectural survey. These are historical figures, not a forecast.
What seismic standard should I look for when buying in Japan?
Look for the New Seismic Standard (新耐震基準), which applies to buildings whose construction confirmation was obtained on or after 1 June 1981. For wood-frame houses, a build from June 2000 onwards also meets a stricter revision covering ground surveys, column-to-foundation hardware and the layout of load-bearing walls.
For registration and acquisition tax purposes, a building recorded as constructed on or after 1 January 1982 is treated as meeting the New Seismic Standard, which qualifies it for the reduced rates. For reinforced-concrete condominiums, which make up most of the central Tokyo market, the 1981 line is the one that matters. A pre-1981 building should have documented seismic retrofitting, and your agent should obtain the structural records before you make an offer.
About the authors
Maximilian Jacob is Research and Content Lead at Housing Japan K.K., a licensed real estate brokerage in Tokyo (Tokyo Governor (3) No. 98912) that has advised international buyers, sellers and tenants in central Tokyo since 2000. He researches the Tokyo prime residential market using primary Japanese sources, including Ministry of Land, Infrastructure, Transport and Tourism (MLIT) transaction and land price data, National Tax Agency (NTA) roadside land valuations, Bank of Japan policy statements and e-Stat national statistics. His work focuses on foreign buyer procedure, property taxation, non-resident financing, and the Minato, Shibuya and Chiyoda luxury markets.
Yudai Yamaguchi is Head of Sales and Head of Property Management at Housing Japan K.K. He has more than a decade of real estate experience across Japan and the United States, spanning development, sales operations, investment, acquisitions, leasing, construction and property management. He previously held management roles at the Open House Group in both countries, including General Manager of its Atlanta office, where he oversaw local real estate operations. He holds a bachelor’s degree in Liberal Arts from Waseda University and studied International Relations at the University of Washington.
Note: Housing Japan is involved in property sales and development in Tokyo. We act in the buyer’s best interest and only recommend properties that align with your needs, circumstances, and goals. Information here is for general guidance and is not legal or tax advice. Always consult a licensed Japanese tax professional for personal advice.
Sources:
Ministry of Finance: FEFTA real property reporting
Ministry of Foreign Affairs: visa exemption list (1 September 2025)
Tokyo Metropolitan Government: benchmark land prices 2026
MLIT: Land Price Publication 2026
IRS: Form 8938 questions and answers